The Milliman Mortgage Repurchase Index (MMRI) is a lifetime repurchase rate estimate calculated at the loan level for single-family mortgages within each quarterly origination vintage. MMRI defines the repurchase rate as the likelihood that a loan will ever be bought back by the seller from the secondary market agencies, Fannie Mae or Freddie Mac. The results of the 2026 Q2 study reflect the most recent acquisition data available from Fannie Mae and Freddie Mac, with measurement dates starting from October 1, 2024.
Key findings
The value of the MMRI for government-sponsored enterprise (GSE) acquisitions increased for both Fannie Mae (from 0.173% to 0.198%) and Freddie Mac (from 0.253% to 0.283%).1
Figure 1: MMRI 2026 Q2 dashboard for GSE loans
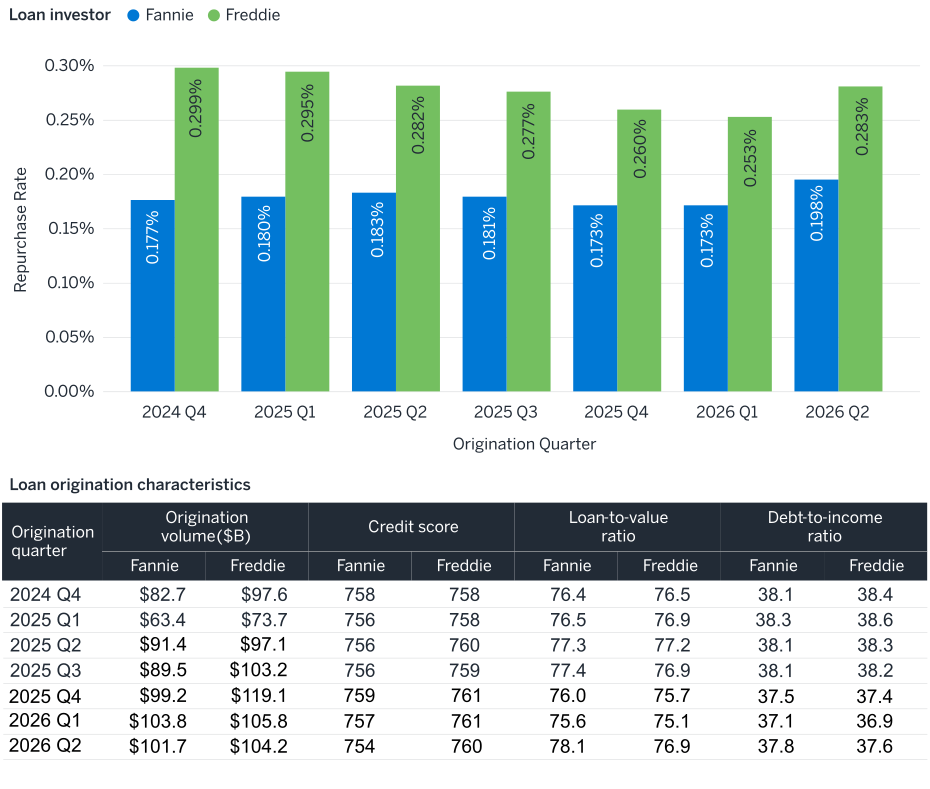
The recent increase in repurchase risk for both Fannie Mae and Freddie Mac represents a reversal of the generally stable or improving trend observed in prior quarters. Although overall repurchase risk remains relatively low, the increase suggests a modest deterioration in underwriting quality and highlights the importance of continued monitoring of loan origination characteristics and credit quality.
Summary of trends
For the 2026 Q2 origination cohort, our latest MMRI results indicate that repurchase risk has increased for both Fannie Mae (+2.5 bps) and Freddie Mac (+3.0 bps). Repurchase risk remained generally stable or improved over several consecutive quarters; however, this trend reversed in the most recent quarter. Notably, Freddie Mac’s repurchase risk remains somewhat higher than Fannie Mae’s, which is consistent with historical patterns. This may be attributable to differences in loan mix, borrower profiles, or underwriting practices between the two GSEs.
Freddie Mac’s most recent defect report (data through Q2 2026) shows that income-driven defects and collateral-related issues account for approximately half of repurchases.2 Fannie Mae also reports that a similar share of repurchases are income-driven, with liabilities-related issues also being significant.3
Defects related to income are common since the GSE selling guides provide absolute requirements on allowable DTI ratios. If an underwriting defect is found and the loan then exceeds the guideline DTI threshold, a loan repurchase is triggered. Figure 2 breaks down the origination volume by DTI for existing loans by origination quarter.
Figure 2: Distribution of DTI by origination cohort ($unpaid principal balance)
| Freddie Mac | Fannie Mae | |||||||
|---|---|---|---|---|---|---|---|---|
| [0,45) | [45,48) | [48,50) | [50,100] | [0,45) | [45,48) | [48,50) | [50,100] | |
| 2024 Q4 | 68.6% | 13.8% | 11.1% | 6.6% | 70.6% | 13.6% | 10.5% | 5.2% |
| 2025 Q1 | 67.7% | 14.2% | 11.5% | 6.7% | 69.8% | 13.8% | 11.0% | 5.4% |
| 2025 Q2 | 69.3% | 13.7% | 10.9% | 6.1% | 70.4% | 13.6% | 10.7% | 5.3% |
| 2025 Q3 | 70.0% | 13.5% | 10.7% | 5.8% | 70.5% | 13.7% | 10.7% | 5.1% |
| 2025 Q4 | 72.9% | 12.6% | 9.6% | 4.9% | 72.8% | 12.8% | 9.7% | 4.6% |
| 2026 Q1 | 74.8% | 12.0% | 8.7% | 4.6% | 74.3% | 12.4% | 9.1% | 4.2% |
| 2026 Q2 | 72.4% | 12.7% | 9.8% | 5.2% | 71.6% | 13.3% | 10.2% | 4.9% |
DTIs have gradually been decreasing over time, with larger shares in the [0, 45) bin relative to the underwriting threshold of 50. This trend has been observed for both Freddie Mac and Fannie Mae originations.
The historical decline in tail share (DTI ≥ 48) was attributable to gradually declining mortgage rates, a trend that has reversed in the most recent quarter. When interest rates fall, the monthly mortgage payment used in the DTI calculation also decreases, all else being equal. The prevailing rate increased from 6.11% in 2026 Q1 to 6.49% in 2026 Q2. Early numbers from 2026 Q3 indicate the 30-year mortgage rate increased to 7.03%.
Figure 3: Average 30-year U.S. mortgage rates
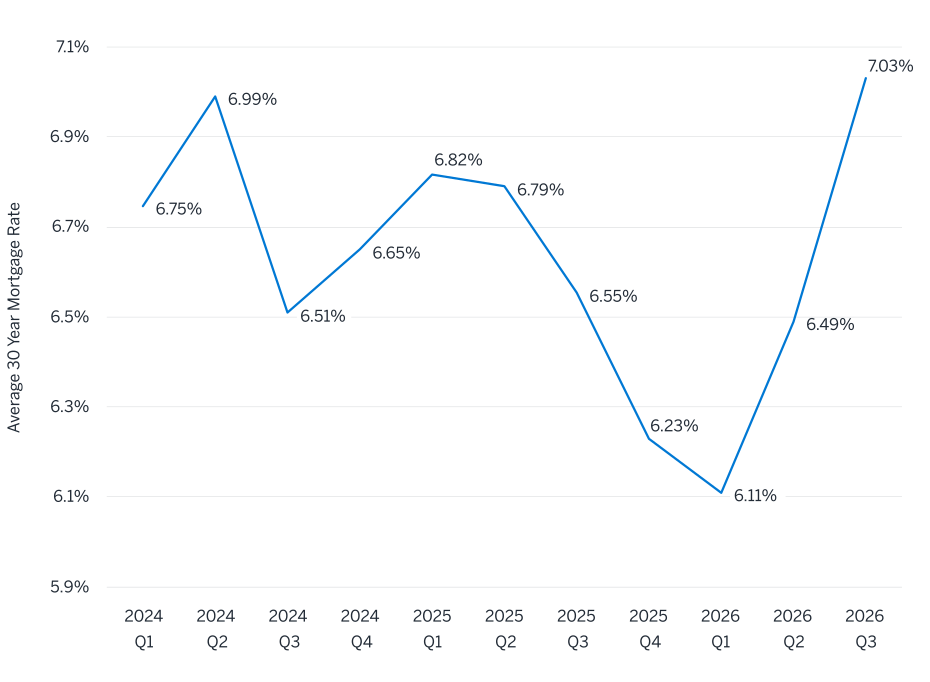
Mortgage rates, as a function of the 10-year Treasury Bill, started to reverse course in early March, 2026 in response to market uncertainty surrounding military conflicts overseas and the resulting oil price shock. The impact on mortgage rates and whether they will continue the declining trend depends on the duration of this shock on financial markets.
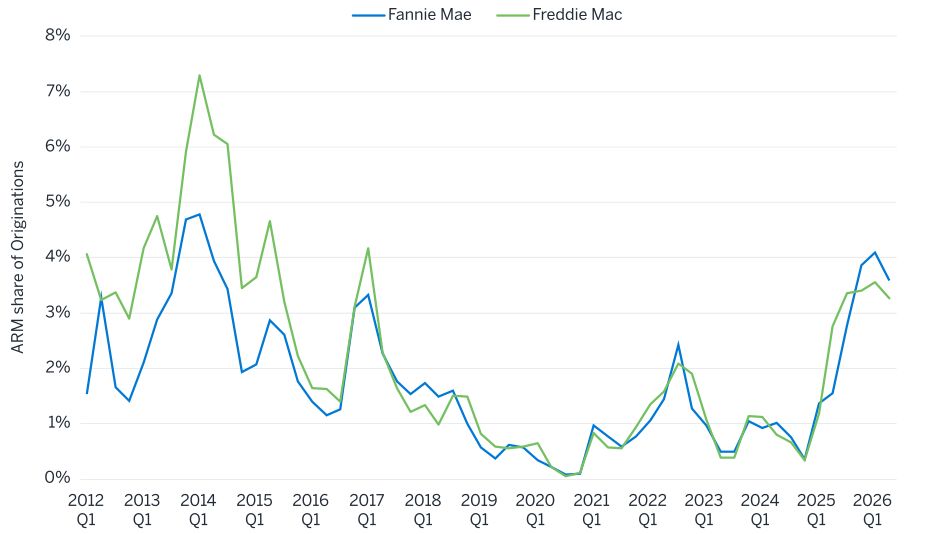
The share of adjustable-rate mortgages (ARMs) as a proportion of all mortgage loans continues to be higher in 2026 for both Fannie Mae and Freddie Mac. The ARM share is relevant to loan repurchases, given the differences in the DTI calculation. This makes the repurchase risk outlook for ARM borrowers more sensitive to shifts in the mortgage rate.
Figure 4: ARM volume as share of acquisition volume, 2012 Q1–2026 Q2
Recent expansions to the appraisal waiver programs announced in 2024 for Fannie Mae and 2025 for Freddie Mac continue to show up in the data for new originations. Figure 5 shows that the trend of the share of loans with appraisal waivers has continued through 2026 Q2.
The appraisal waiver shares generally increased for both Fannie Mae and Freddie Mac through Q1 2026, reaching approximately a quarter of newly originated conventional mortgages purchased by the GSEs. However, this trend reversed in Q2 2026, with appraisal shares declining for both GSEs.
Figure 5: Percentage of originations with an appraisal waiver
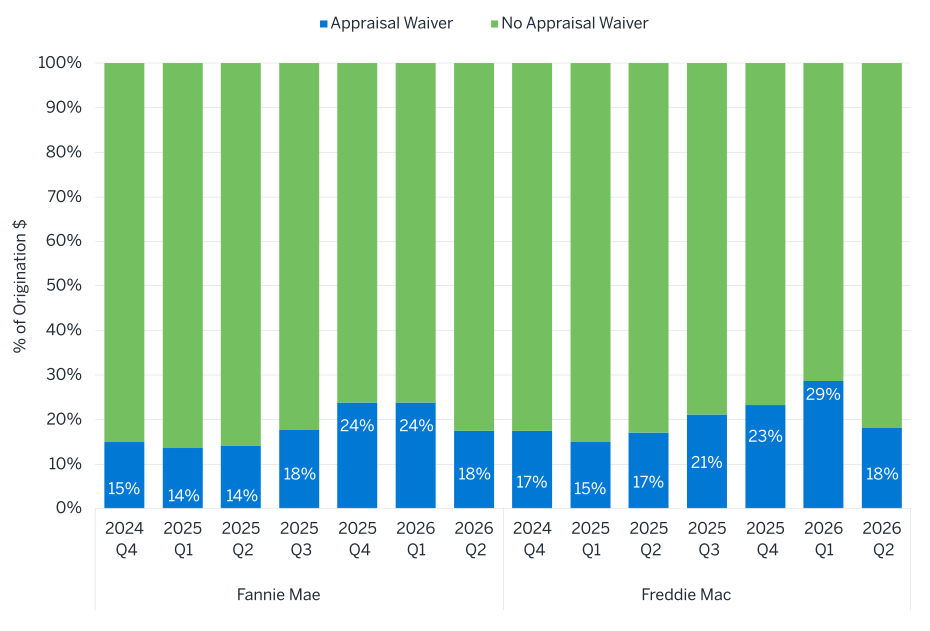
Loans need to qualify to receive an appraisal waiver based on more rigorous credit standards. As a result, repurchase rates on appraisal waivers tend to be lower relative to other property valuation methods. If the appraisal was waived, it is also not possible to have an appraisal-related defect. All else equal, the volume with an appraisal waiver is expected to increase with the expanded eligibility standards. We will monitor if these loosened credit guidelines result in an increase in repurchase rates.
Both Fannie Mae and Freddie Mac have continued to develop tools to allow for streamlined quality control at mortgage underwrite. Fannie Mae recently announced additions to its Desktop Underwriter® system to offer rep and warrant relief for defects related to undisclosed liabilities outside the mortgage payment.4 Freddie Mac has also released its Quality Control Advisor Plus platform to help automate traditionally error-prone aspects of the underwriting process for lenders.5 Both programs could help reduce the cost and incidence of actual repurchase risk.
Another trend to monitor is the introduction of VantageScore 4.0 and FICO 10T for underwriting new mortgages. It is unknown how introducing modernized credit scores to mortgage underwriting will affect loan-repurchase activity.
About the MMRI
Milliman is an expert in analyzing complex data and building transparent, intuitive, and informative econometric models. We have used our expertise to assist multiple clients in developing econometric models for evaluating mortgage risk, both at the point of sale and for seasoned mortgages.
The MMRI uses econometric modeling to develop a dynamic model that clients can apply in multiple ways. Because the MMRI produces a lifetime repurchase-rate estimate at the loan level, clients use it as a benchmarking tool in loan-defect pricing. The repurchase-scoring methodology is constructed separately for repurchases that occurred while loans were either performing or delinquent. For new-origination cohorts, Milliman applies these scoring methodologies and weights them using the probability the loan will roll into serious delinquency. In addition, Milliman uses a mix of borrower attributes and loan characteristics to identify trends most associated with loan repurchase.
Milliman is one of the largest independent consulting firms in the world and has pioneered strategies, tools, and solutions worldwide. We are recognized leaders in the markets we serve. Milliman insight reaches across global boundaries, offering specialized consulting services in mortgage banking, employee benefits, healthcare, life insurance and financial services, and property and casualty (P&C) insurance. Within these sectors, Milliman consultants serve a wide range of current and emerging markets. Clients know they can depend on us as industry experts, trusted advisers, and creative problem-solvers.
Milliman's Mortgage Practice is dedicated to providing strategic, quantitative, and other consulting services to leading organizations in the mortgage banking industry. Past and current clients include many of the nation's largest banks, private mortgage guaranty insurers, financial guaranty insurers, institutional investors, and governmental organizations.
1 Please note the MMRI reflects Milliman’s proprietary model-based estimates and not actual mortgage repurchase results.
2 Freddie Mac loan delivery & repurchase trend reporting. (2026, Q2). Freddie Mac. Retrieved November 17, 2026, from loan-reporting-data-trends-q2-2026.pdf.
3 Dedicated to building better loan quality. (n.d.). Fannie Mae. Retrieved November 17, 2026, from https://singlefamily.fanniemae.com/originating-underwriting/loan-quality.
4 Enhancing efficiency: Undisclosed liabilities in Desktop Underwriter. (2025, November 17). Fannie Mae. Retrieved November 17, 2026, from https://singlefamily.fanniemae.com/originating-underwriting/loan-quality/quality-insider/november-2025.
5 Freddie Mac announces QC enhancement tool. (2025, November 19). Freddie Mac. Retrieved November 17, 2026, from https://nationalmortgageprofessional.com/news/freddie-mac-announces-qc-enhancement-tool.